BASED IN GLOUCESTER · CLIENTS ACROSS THE UK
Remortgage Advice
Is it time to review your mortgage?
Your mortgage is probably one of your biggest financial commitments, but when did you last review it?
Perhaps your current fixed-rate deal is coming to an end. Maybe your monthly payments have increased, your circumstances have changed or you’re simply wondering whether a better option is available.
Whatever your reason for reviewing your mortgage, I’ll help you understand the options available and whether switching your mortgage could be right for you.
Based in Gloucester, I provide personal remortgage advice to clients locally and throughout the UK.
Let’s make sure your mortgage still works for you.
When should you consider remortgaging?
There are several reasons why reviewing your mortgage could make sense.
Your current fixed-rate deal is ending
When a fixed-rate mortgage comes to an end, your lender may move you onto its Standard Variable Rate (SVR), unless you arrange another deal.
This could mean your monthly payments increase.
It's worth reviewing your options in advance so you have time to consider a new mortgage deal before your existing rate expires.
You want to reduce your monthly payments
Depending on interest rates, your mortgage balance, property value and circumstances, switching to another mortgage product could reduce your monthly repayments.
We'll look at the available options and consider the overall cost, not just the headline interest rate.
Your circumstances have changed
Perhaps your income has increased, you've paid off other borrowing or your family circumstances have changed.
A review could help establish whether your current mortgage remains suitable.
You want to release equity from your property
If your property has increased in value or you've reduced your mortgage balance, you may have built up equity.
Depending on affordability and lender criteria, it may be possible to borrow additional funds for purposes such as home improvements or other planned expenditure.
Additional borrowing will increase the amount secured against your property and may increase your monthly repayments and overall interest costs.
Remortgage with your existing lender or switch?
You may have two main options when your current deal ends.
Product transfer
A product transfer involves moving onto a new mortgage deal with your existing lender.
It can sometimes be a straightforward process, but it's still important to understand whether the available deal is competitive and suitable for you.
Remortgaging to a new lender
Switching to another lender could provide access to different mortgage products or features.
However, a new application will normally involve affordability and eligibility checks, and there may be valuation, legal or other costs.
I’ll help you compare the options so you can make an informed decision.
How does the remortgage process work?
1
Review your current mortgage
We'll look at your outstanding mortgage balance, current interest rate, remaining mortgage term and when your existing deal ends.
2
Understand your circumstances
I'll take the time to understand your income, expenditure, property value and what you want your mortgage to achieve.
3
Explore the available options
I'll research suitable mortgage products and help you compare the costs, rates, features and lender criteria.
4
Arrange your new mortgage
If you decide to proceed, I'll guide you through the application process and help you understand the information and documents required.
5
Complete your remortgage
Once your new mortgage has been approved and the necessary legal work completed, your new mortgage can take effect.
Thinking about borrowing more?
A remortgage may provide an opportunity to raise additional funds, subject to affordability, lender criteria and the purpose of the borrowing.
You may be considering:
- Home improvements or an extension.
- Debt consolidation.
- Helping family members financially.
- Funding another property purchase.
It’s important to consider the implications carefully. Consolidating unsecured debts into a mortgage can mean paying more interest over a longer period, and the borrowing becomes secured against your home.
I’ll help you understand the options, costs and risks before making a decision.
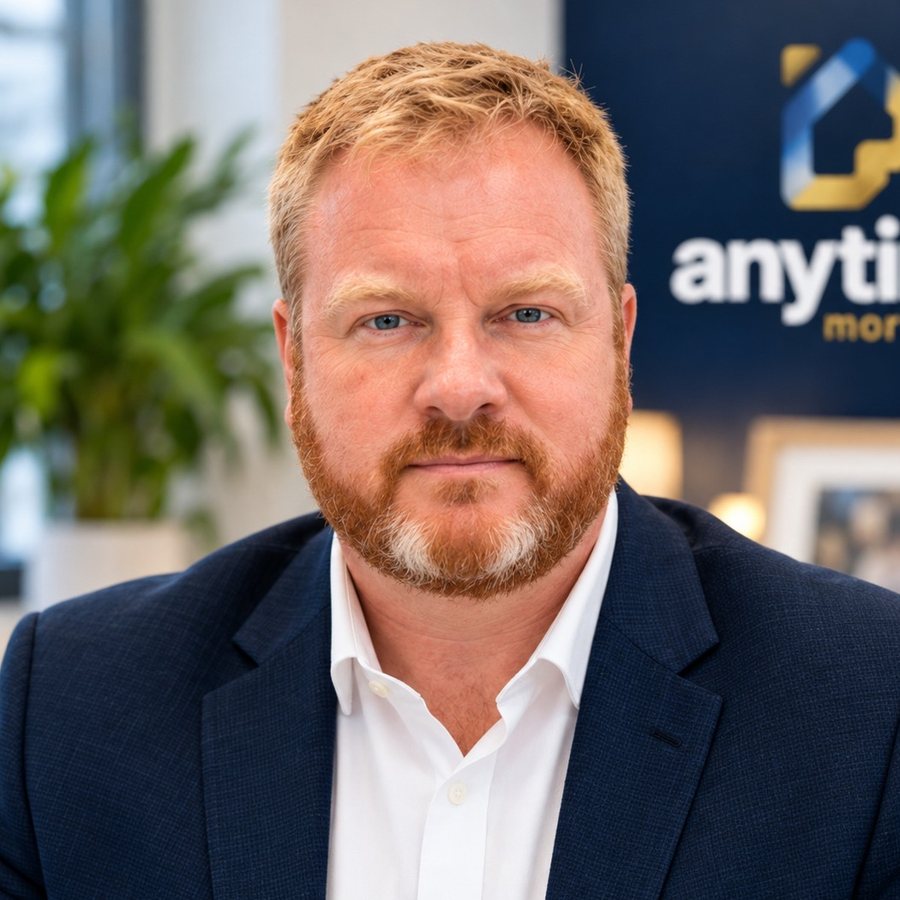
Why review your mortgage with Andrew Westwood?
With 30 years of experience in financial services, I understand how important it is to make informed decisions about your finances.
My approach is personal, straightforward and focused on your individual circumstances.
- Advice tailored to your needs.
- Help comparing mortgage options.
- Clear explanations of costs and features.
- Support throughout the application process.
- Based in Gloucester, supporting clients across the UK.
Remortgage FAQs
When should I start looking at remortgaging?
It's sensible to start reviewing your options around six months before your current mortgage deal ends. This gives you time to explore options and potentially secure a new rate in advance, subject to the lender's offer validity period.
Do I have to remortgage when my fixed rate ends?
No. You may be able to arrange a product transfer with your existing lender or consider moving to another lender. The right option depends on your circumstances.
Will I need another property valuation?
This depends on the lender and the remortgage product. Some lenders use automated valuations, while others may require a physical valuation.
Can I remortgage if I'm self-employed?
Yes, self-employed applicants can remortgage, subject to the lender's affordability and income evidence requirements.
Can I borrow more when I remortgage?
Potentially. Additional borrowing is subject to affordability, lender criteria, property value and the purpose of the funds.
Will I have to pay legal fees?
Some remortgage products include legal services, while others may involve legal costs. There may also be valuation, arrangement or early repayment charges to consider.
Can I remortgage if my property value has fallen?
It may still be possible, but the available options will depend on your outstanding mortgage balance, current property value and the lender's criteria.
Is your mortgage deal coming to an end?
Don’t leave it until the last minute.
Let’s review your current mortgage and explore whether there may be a more suitable option available.